
Nearly $2,000 a month buys Jack Bryant 760 square feet in Cool Springs.
He wants room to start a family. He also wants to stay in the place where he grew up. Buying feels difficult, but continuing to rent worries him, too.
That was the human story in WSMV’s November 13 report about Franklin appearing in a national housing article.
The headline was about a ranking. Bryant’s problem was more immediate: finding a home that lets him keep living his life here.
There are Franklin listings below $500,000. But a lower asking price answers only part of that problem. A $400,000 condominium can still carry a monthly bill above $2,500 before property taxes and insurance, depending on the financing.
For someone buying a first home, downsizing or helping an adult child explore options, that gap is worth checking.
What the Franklin Housing Headline Actually Means
Franklin appears second, after Scottsdale, Arizona, in FinanceBuzz’s list of 11 cities that could become unaffordable in 2027.
Second on that list doesn’t make Franklin America’s second least affordable city.
FinanceBuzz gives Franklin an average home value of $913,277 and median gross rent of $2,111. Its editor’s note identifies the home values as Zillow figures from September 2026 and the rents as City-Data figures from 2024.
Those numbers describe different measures from different periods. They are not predicted prices for 2027, and average home value is not the same as the median price of homes sold.
It says nothing about that household’s down payment, existing debts, space needs or willingness to consider a condominium.
Our look at Tennessee’s affordability and quality-of-life rankings explains why statewide labels can conceal very different household budgets. For a Franklin search, the useful next step is to examine individual properties and their full costs.
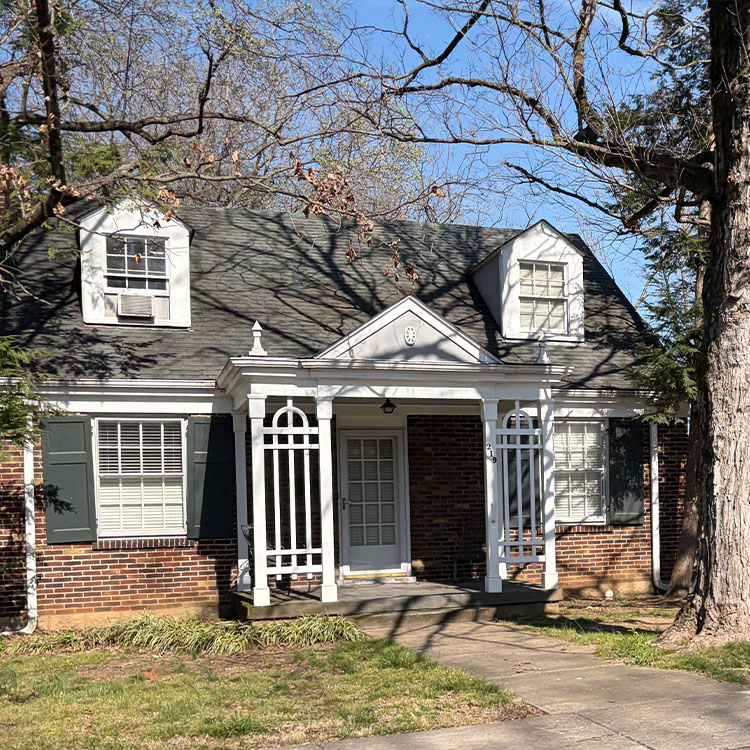
Two Listings Show the Choices Below $500,000
These brokerage pages showed both properties as active when checked November 15, 2026.
| Property | Advertised price | Listed home | Monthly HOA |
|---|---|---|---|
| 1942 Turning Wheel Lane | $400,000 | Two-bedroom, two-bath condominium; 1,352 square feet | $265 |
| 743 Huffine Manor Circle | $499,000 | Three-bedroom condominium; 1,818 square feet | $215 |
Prices, availability and association charges can change. These are two advertised examples with Franklin mailing addresses, not a representative market sample or property recommendations.
Both offer more than one bedroom. Both are condominiums. That is the useful finding: a search below the citywide home-value figure can reveal options, but the property type may be part of the compromise.
For a growing household, another bedroom might make staying possible. For someone downsizing, the question may be whether less space also means less work and a manageable monthly bill.
The lower-priced example also has the higher HOA fee. That does not make it a worse purchase. It shows why sorting listings by asking price is only the beginning.
The listings cannot establish what Bryant could afford. His income, debts and savings are unknown.
What a $400,000 Condo Could Mean Each Month
Consider an illustrative purchase of the $400,000 property.
Assume a 10% down payment, a 30-year fixed mortgage and a 6.5% interest rate. The rate is an example for this calculation, not a current quote or a prediction.
| Part of the example | Amount |
|---|---|
| Down payment | $40,000 |
| Mortgage amount | $360,000 |
| Monthly principal and interest | About $2,275 |
| Advertised monthly HOA | $265 |
| Principal, interest and HOA subtotal | About $2,540 a month |
That subtotal still excludes property taxes, homeowners insurance, mortgage insurance if required, maintenance, repairs and utilities. The down payment also excludes closing costs and any cash reserves the buyer needs.
The Consumer Financial Protection Bureau’s homebuying budget guide explains the expenses to include when building a complete ownership budget.
This example shows why “below Franklin’s average home value” and “within my budget” are separate questions. Even with $40,000 available for a down payment, this buyer would have substantial costs beyond the advertised price.
It also explains why a renter should resist comparing rent with a mortgage calculator’s principal-and-interest figure alone. Put the complete costs beside each other before deciding whether buying creates more breathing room.
Find Out What the HOA Fee Actually Buys
At $265 a month, Turning Wheel Lane’s advertised HOA charge totals $3,180 a year. Huffine Manor Circle’s $215 charge totals $2,580, assuming neither changes.
Multiplying the fee is easy. Understanding what it covers takes more work.
Before making an offer, request the association’s governing documents, current budget and information about reserves, planned projects and assessments. Ask which expenses belong to the association and which remain yours.
Check whether water is included or billed separately, and identify the utility serving the address. Our coverage of Franklin’s water supply and household conservation explains why the provider on the bill matters.
A lower fee is not automatically better if it leaves you responsible for costs another association covers. A higher fee is not automatically good value, either.
For someone downsizing, this is especially relevant. You may be hoping to exchange yardwork and exterior upkeep for a predictable monthly charge. Confirm that the arrangement actually does that.
Then look at how the home works day to day. Turning Wheel Lane’s listing describes an upper-level flat. If stairs matter now, or could matter later, check the access before treating the price as a solution.
A manageable payment cannot compensate for a home you struggle to enter.
Separate the Cash Needed to Buy From the Cost of Staying
A household can face two different barriers: enough cash to close and enough income to carry the home afterward.
Down-payment assistance may help with the first while leaving the second unresolved.
The Tennessee Housing Development Agency’s Great Choice Plus program offers down-payment and/or closing-cost assistance through a second mortgage for borrowers who qualify for a Great Choice home loan. THDA describes deferred and repayment options.
Start with THDA’s assistance information and a THDA-approved lender. Ask for a comparison showing:
- Cash needed at closing with and without assistance.
- The combined monthly payment, including any second mortgage.
- What becomes due if you sell or refinance.
- Current Williamson County income and purchase-price limits.
Homebuyer education is required for Great Choice and Great Choice Plus loans. Household and property eligibility also need to be checked.
The useful measure is what the assistance changes in your own budget. Less cash required upfront can be valuable, but any added monthly obligation belongs in the decision from the start.
Habitat Offers a Different Route Into Homeownership
Habitat for Humanity Williamson-Maury has a homeownership program for eligible households, with preparation and participation requirements.
Its published eligibility information requires completion of the Get Ready program before applying. Applicants must meet requirements involving housing need, ability to pay, credit, savings and participation.
A qualifying connection through residence or employment in its service counties is required for at least 12 months before applying. Williamson County is included.
Paying more than 30% of income toward rent is one listed example of housing need. It does not establish eligibility by itself.
Think of this as a separate application path, rather than assistance to attach to either listing above. Ask about preparation, application timing, anticipated home locations and financial obligations. Acceptance and a home inside Franklin city limits are not guaranteed.
That location question matters for someone whose main goal is remaining close to family, work or an established support network.
Make Sure the Home Preserves What You Want to Stay For
“Staying in Franklin” can mean keeping the same mailing address. It can also mean staying near a daughter, a familiar doctor, a job or friends who help with everyday life.
Write down the connections you want to preserve before widening your search.
Then test each property against them. Check the actual drive to work, groceries and appointments at the times you would travel.
If a job change is part of your plan to stay, our guide to In-N-Out’s Franklin headquarters and how to investigate its jobs offers one local starting point. Confirm current openings and pay before including a possible new job in your housing budget.
For a hypothetical household, adding 20 minutes each way to a five-day commute means 3 hours and 20 minutes more driving each week. A cheaper home may still be worth it. Make that trade knowingly.
If a dog is part of your household, check the condominium’s pet rules and everyday walking options, too.
These details determine whether a smaller or different home preserves the life you hoped to keep.
Look for Negotiating Room in the Right Price Range
Real estate agent Kate Goerlinger told WSMV that high interest rates could challenge sellers in 2027, with longer listing times potentially helping buyers depending on price range.
The station also reported that homes around $500,000 sell quickly.
That difference matters. A buyer looking at a $400,000 condominium should not assume the seller faces the same conditions as someone listing a much more expensive house.
Ask for recent closed sales of similar properties, price reductions, listing histories and documented seller concessions when available. Compare condominiums with comparable condominiums.
Have the lender explain how any proposed concession would affect your cash needed at closing and monthly costs. The CFPB’s guide to comparing Loan Estimates can help you assess financing offers on consistent terms.
Before booking several showings, choose one candidate home and build its complete budget. Identify the upfront cash, recurring expenses, access needs and daily drives. Then investigate assistance and financing against that specific example.
You may find a workable route to staying. You may find that another year of renting gives you time to prepare. Either conclusion is more useful when it comes from a household budget and a real address.
More from Real Tennessee Life…
Tennessee Returned a Record 169,303 Unclaimed Property Claims. So Why Did the Checks Get Smaller?
Three Liver Transplants in 12 Hours: How Vanderbilt’s Team Did It and Why Nashville’s Transplant Center Is the Nation’s Busiest